California box truck operators face a two-part insurance challenge before putting trucks on delivery routes. Coverage must satisfy state compliance requirements while protecting business risks of hauling goods. A 16-foot box truck delivering appliances, a 26-foot truck handling local moves, and a refrigerated truck carrying restaurant supplies can all require different liability limits, cargo protection, and additional coverage layers.
Insurance is not just a renewal task for California carriers starting operations. Before beginning service, delivery or moving companies must handle Motor Carrier Permit requirements, including proof of insurance. Building the right coverage package means understanding which policy types address which operating exposures and how California regulations set baseline requirements.
Key Takeaways
California box trucks typically require a coverage package rather than a single policy. Box truck insurance combines liability protection with vehicle and cargo coverage options. Each coverage type addresses a different risk: liability covers accidents, physical damage covers the truck itself, and cargo coverage protects goods in transit.
Delivery and moving companies should match coverage layers to their specific operations. A financed truck hauling high-value furniture needs different protection than an owned truck delivering retail parcels. Understanding each coverage type helps operators build cost-effective packages without leaving critical exposures unprotected.
Primary auto liability covers bodily injury and property damage caused by truck operations. This coverage is required for California Motor Carrier Permit proof of financial responsibility. Primary liability coverage responds when a box truck is at fault in an accident that injures others or damages property.
California uses Combined Single Limit coverage for liability requirements rather than split limits. A CSL policy provides one total limit applying to all damages in a single accident. The required CSL amount depends on truck weight and cargo type, with minimums ranging from $300,000 to $750,000 for most non-hazardous delivery and moving operations.
Physical damage coverage protects the box truck itself through collision and comprehensive protection. Collision covers damage from accidents regardless of fault, while comprehensive covers theft, fire, vandalism, and weather damage. Physical damage is separate from liability and does not cover injuries or property damage to others.
Financed trucks typically require physical damage coverage with the lender named as loss payee. A total loss or extended downtime can devastate operations if the truck represents the primary income source. Owners must weigh premium cost against replacement value and the financial impact of losing the truck.
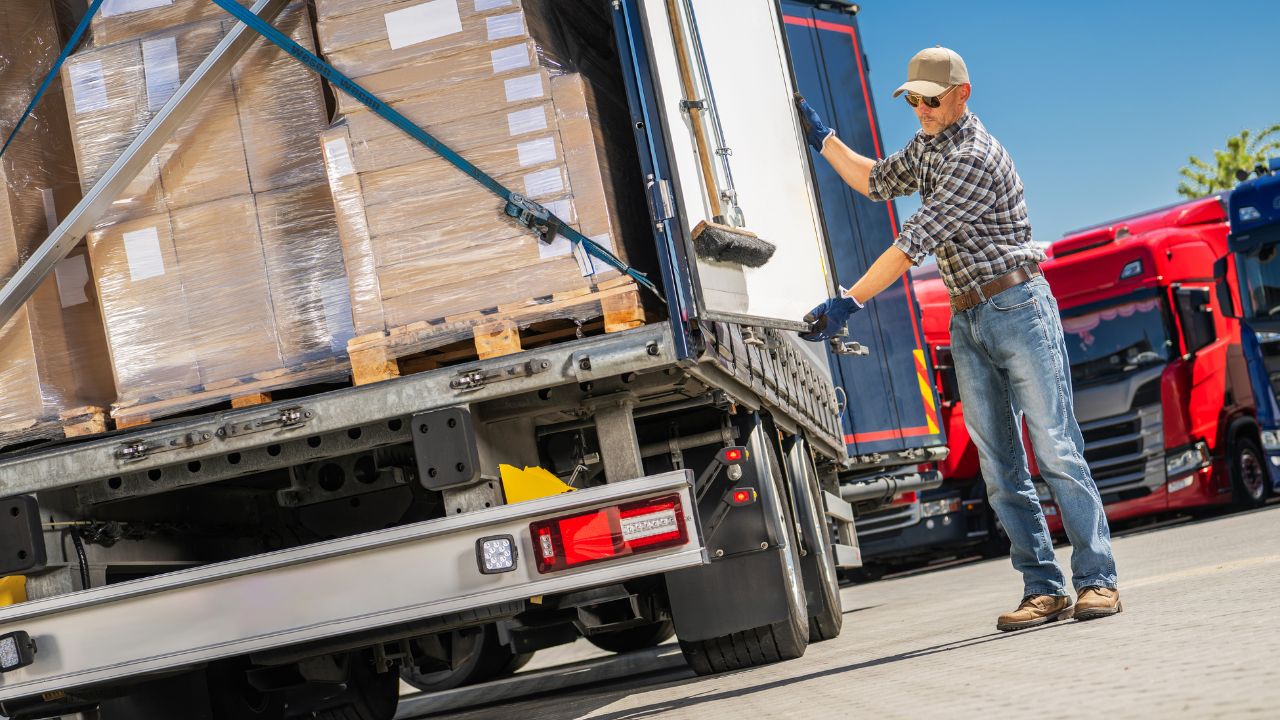
Motor truck cargo insurance covers loss, damage, or theft of goods being hauled. Motor truck cargo insurance responds when customer property is damaged during loading, transit, or unloading. Cargo limits should reflect the highest realistic load value rather than just average shipments.
Delivery companies hauling appliances, furniture, electronics, or business inventory face cargo exposure on every route. Moving companies handling household goods should verify whether additional valuation requirements apply. Customers and shipping contracts often require proof of cargo coverage before allowing carriers to handle goods.
Primary auto liability and cargo coverage form the baseline, but additional exposures exist beyond vehicle accidents. Delivery crews entering customer sites, loading dock operations, and employee injuries create business risks that basic truck policies may not address. Truckers general liability insurance and workers' compensation fill important gaps.
Operations involving multiple drivers, helpers, or movers raise the number of insurance considerations. Some exposures are policy-specific, while others are driven by California regulatory requirements. Operators should review business activities carefully before assuming truck liability alone provides complete protection.
Truckers general liability covers non-auto business exposures such as premises operations and customer-site incidents. This coverage addresses allegations related to loading and unloading activities when the claim falls outside auto liability. A delivery driver damaging a customer's flooring or a mover breaking property while carrying items up or down stairs can trigger general liability rather than auto coverage.
Policy language varies by carrier and must not be treated as a substitute for auto liability or cargo. Customer-site incidents may involve property damage, bodily injury, or advertising injury claims. Businesses regularly entering homes, apartments, warehouses, or job sites should review general liability options carefully.
California DMV Motor Carrier Permit applications require proof of workers' compensation insurance or a signed exemption. Workers' compensation covers medical costs and lost wages when employees are injured on the job. Carriers using drivers, helpers, movers, or loaders should not treat truck insurance as the only required coverage.
Crew and labor exposure increases significantly for moving companies and delivery operations involving two-person teams. Misclassifying employees as independent contractors creates serious liability and regulatory risk. Operators should verify employment status and coverage obligations before putting crews on the road.
Non-trucking liability and bobtail insurance apply primarily to truckers operating under a motor carrier's authority rather than their own. These coverages fill gaps when a truck is not under dispatch or hauling cargo. Independent box truck operators owning their operating authority typically do not need non-trucking or bobtail policies.
Owner-operators who sometimes lease on to another carrier should verify whether gaps exist between primary liability and non-trucking liability. Most delivery and moving companies operating box trucks under their own authority can focus on primary auto liability instead. Reviewing the specific operating scenario with an agent helps avoid paying for unnecessary coverage or leaving gaps.
California box truck insurance requirements are driven by state Motor Carrier Permit rules and federal regulations for certain operations. Liability limits are not one-size-fits-all; they range from $300,000 to $5 million depending on vehicle specifications and cargo. Adapting to California regulatory changes requires operators to verify current requirements before beginning operations.
New carriers must apply for an MCP before starting delivery truck insurance operations in California. The Motor Carrier Permit application includes an insurance checklist that must be satisfied before the permit is issued. Understanding these compliance checkpoints helps operators gather correct documentation and avoid delays when launching or adding trucks.
A Motor Carrier Permit is a California DMV permit required before carriers begin intrastate for-hire operations. New carriers must apply for an MCP and provide proof of insurance as part of the application. The MCP will not be issued until all requirements, including insurance documentation, are met.
Mail applications require obtaining a CA number from the California Highway Patrol before submitting paperwork. Electronic applications streamline the process but still require meeting insurance and safety requirements. Operators should verify MCP applicability for their specific business model before assuming exemption.
California liability insurance varies from $300,000 to $5,000,000 CSL depending on vehicles and property transported. Property other than hazmat in vehicles 10,000 pounds GVWR or less, for-hire carriers only, requires a $300,000 CSL minimum. Property other than hazmat in vehicles 10,001 pounds GVWR or more requires $750,000 CSL minimum.
| Truck and Cargo Category | GVWR / Basis | Minimum CSL Required |
| Non-hazmat cargo, for-hire only | 10,000 lbs GVWR or less | $300,000 CSL |
| Non-hazmat cargo, general operations | 10,001 lbs GVWR or more | $750,000 CSL |
| Federal interstate for-hire freight | 10,001+ lbs GVWR | $750,000 minimum |
| Federal household goods cargo liability | Per vehicle / per occurrence | $5,000 / $10,000 |
Federal interstate for-hire property carriage with 10,001+ GVWR freight vehicles requires $750,000 minimum. Federal household goods cargo liability requirements list $5,000 per motor vehicle and $10,000 per occurrence. Operators should verify exact limits for their truck weight and cargo type rather than assuming a single minimum applies.
A CA number is issued by the California Highway Patrol and required for certain motor carrier applications. The Basic Inspection of Terminals Program, administered by CHP, may apply to specific carrier configurations. Operators should verify whether BIT inspection obligations apply to their fleet before beginning operations.
An EPN requester code is required if the carrier employs drivers with certain CDL or endorsement profiles. Workers' compensation proof or a signed exemption must accompany the Motor Carrier Permit application. Gathering these documents in advance prevents delays when applying for operating authority or adding trucks.
| Document | When It Applies |
| CA Number | Required for certain motor carrier applications, issued by the California Highway Patrol |
| BIT Inspection | May apply to specific carrier configurations under the Basic Inspection of Terminals Program |
| EPN Requester Code | Needed if the carrier employs drivers with certain CDL or endorsement profiles |
| Workers' Compensation Proof or Exemption | Must accompany every Motor Carrier Permit application |
Delivery and moving companies may operate similar box trucks but face different coverage priorities and regulatory considerations. Appliance delivery, retail parcel routes, contractor supply delivery, and local household moves each create distinct cargo exposures. Moving company truck insurance requires additional attention to customer-property handling and valuation rules.
Certificate requirements also differ based on contract types. Delivery platforms, warehouses, brokers, property managers, and commercial clients may each require specific liability limits or additional insured endorsements. Understanding these differences helps operators avoid underbuying coverage or facing contract delays due to insufficient limits.
Appliance and furniture delivery involves higher cargo values, customer-home entry, and loading/unloading exposure in tight spaces. Retail and parcel routes feature frequent stops, multiple drivers, and route radius that varies by contract. Contractor and supply delivery operations face tools and materials exposure plus job-site incidents that may trigger general liability.
Refrigerated or food delivery may require temperature-control or spoilage endorsements depending on carrier and policy language. Certificate requirements vary significantly by delivery platforms, warehouses, brokers, property managers, and commercial clients. Operators should gather contract insurance requirements before quoting to ensure coverage meets all client specifications.
Treating moving companies as generic delivery operations creates coverage gaps and regulatory risk. Customer-property handling exposure for moving companies differs from delivering packaged goods to a loading dock. Household goods carriers may face valuation obligations that exceed standard cargo coverage limits.
Box truck insurance for movers must account for home entry, furniture handling, and potential damage during tight-space maneuvering. Crew size and labor exposure also tend to be higher for moving operations than single-driver delivery routes. Moving companies should verify state-specific household-goods carrier requirements before assuming standard delivery coverage is sufficient.
Household goods valuation and cargo rules should be verified before a moving company quotes insurance or begins operations. Federal regulations list specific cargo liability amounts for household goods carriers, but state rules may also apply. Operators should not rely solely on standard motor truck cargo policies without confirming coverage matches household-goods obligations.
California Public Utilities Commission rules may affect intrastate household goods movers in ways that differ from general freight carriers. Verifying these requirements with a California-focused agent prevents coverage gaps and regulatory violations. Moving companies should treat household goods as a special cargo category requiring separate review.
Accurate quotes require accurate information about truck specifications, operating details, and business structure. Commercial trucking insurance underwriters use truck weight, cargo type, radius, driver history, and contract requirements to assess risk. Incomplete or incorrect information can result in inaccurate quotes or coverage gaps when operations begin.
Operators should gather documentation before contacting agents rather than guessing at key details. GVWR, operating authority type, cargo descriptions, and driver information all affect pricing and coverage options. Collecting these details upfront leads to faster quotes and policies that match actual operations.
GVWR stands for Gross Vehicle Weight Rating and is found on the door jamb VIN plate, registration, or dealer listing. Truck GVWR determines which liability tier applies under California and federal financial responsibility rules. Trucks with 10,000 pounds GVWR or less versus 10,001 pounds GVWR or more face different liability minimums.
Many box trucks fall into the 10,001+ GVWR category, triggering higher minimum liability requirements. Operators should verify exact GVWR before assuming their truck qualifies for lower limits. Registration documents and door-jamb plates provide the official GVWR used by regulators and insurers.
Determining whether an operation is for-hire, private carriage, delivery service, or household goods moving affects regulatory and insurance requirements. Identifying what goods are hauled and calculating typical and maximum load value helps set appropriate cargo limits. For-hire carriers face different compliance obligations than private carriage operations.
Intrastate California operations face state MCP requirements, while interstate operations may trigger federal financial responsibility rules. Underwriters need cargo descriptions detailed enough to identify hazardous materials, high-value goods, or special handling requirements. Vague descriptions like "general freight" or "miscellaneous cargo" can result in incomplete coverage or higher premiums.
Defining radius and territory using ZIPs, terminals, and states helps underwriters assess geographic risk and certificate needs. Listing who drives and helps load or unload clarifies employee versus independent contractor status. Checking whether contracts require certificates or additional insureds prevents surprises when customer paperwork arrives.
Determining if the truck is financed or leased affects physical damage requirements and lender documentation needs. Not listing all drivers creates coverage gaps if an unlisted driver has an accident. Operators should provide complete driver information, including license status, experience, and any accident or violation history.
Box truck buyers often focus on the truck purchase while treating insurance as an afterthought. This approach leads to coverage gaps, compliance delays, and unexpected costs when operations begin. Understanding common mistakes helps operators make informed decisions before committing to a truck or launching service.
Insurance mistakes can be expensive to fix after the fact, especially if a claim occurs before gaps are corrected. Some errors result from misunderstanding coverage types, while others stem from incomplete information gathering. Avoiding these mistakes requires planning insurance requirements alongside vehicle selection and business structure.
Choosing state minimum limits blindly ignores cargo value and contract requirements that may exceed baseline regulations. A serious accident can easily exceed $300,000 or even $750,000 in damages when multiple parties are injured. Ignoring cargo value leaves operators personally liable when load value exceeds policy limits.
Customer contracts often require liability limits higher than state minimums before awarding delivery or moving work. Buying minimum coverage and increasing limits later can delay contracts and result in higher premiums. Operators should verify both regulatory minimums and typical contract requirements before selecting limits.
Buying insurance after purchasing a truck creates financing complications and coverage gaps during the critical startup period. Lenders require proof of physical damage coverage before releasing funds or transferring title. Operating even briefly without proper coverage creates enormous personal liability and regulatory risk.
Some insurance companies require inspection or specific truck conditions before binding coverage on older or high-mileage vehicles. Discovering coverage obstacles after purchasing a truck can delay operations and create financial stress. Operators should obtain insurance quotes and conditional commitments before finalizing truck purchases.
Confusing general liability with auto liability creates dangerous coverage gaps for delivery and moving operations. Auto liability covers vehicle accidents, while general liability covers business operations and premises exposures. Neither coverage type substitutes for the other, and both may be needed depending on business activities.
Missing contract certificate language results in delays when customers request proof of insurance with specific endorsements or limits. Operators should review contract insurance requirements before binding policies to ensure coverage matches specifications. Adding endorsements later can trigger additional premiums and underwriting review.
SoCal Truck Insurance specializes in commercial truck insurance for California delivery and moving companies operating box trucks. With 25 years serving the trucking industry, the agency understands how regulatory requirements and business operations shape coverage needs. Every client works with a dedicated agent who provides personalized support throughout the policy term.
Coverage options include primary auto liability, physical damage, motor truck cargo, truckers general liability, and workers' compensation coordination. Spanish-language support is available through box truck policy for operators who prefer conducting business in Spanish. The agency provides 24/7 support for claims and urgent coverage questions.
California box truck insurance requires aligning three priorities: regulatory compliance, cargo protection, and operational risk management. Liability minimums set by truck weight and cargo type form the compliance baseline. Cargo values and customer contracts determine whether additional coverage layers are needed beyond minimum requirements.
Delivery and moving companies face distinct coverage priorities based on how trucks earn revenue and what exposures exist beyond vehicle accidents. Understanding these differences helps operators build cost-effective packages that protect assets without paying for unnecessary coverage. Gathering complete truck, cargo, driver, and contract information before quoting leads to accurate pricing and policies that match operations.
Before you buy, lease, or operate a box truck on California routes, verify your exact insurance requirements using truck weight, cargo type, and contract specifications. SoCal Truck Insurance helps delivery and moving companies compare coverage options and prepare certificates needed to operate or bid on work. Contact SoCal Truck Insurance at (888) 531-2855 or visit the Downey office at 8135 Florence Ave #101, Downey, CA 90240.
Piecing together liability limits, cargo protection, and Motor Carrier Permit paperwork on your own takes time you would rather spend on the road. SoCal Truck Insurance has spent 25+ years placing coverage for California box truck operators, and every policyholder works with a dedicated agent who knows delivery and moving operations inside and out. Get a free quote today, or contact SoCal Truck Insurance directly at (888) 531-2855. Bilingual agents are available 24/7, so help is always one call away, whether you are licensing your first box truck or adding another to a growing fleet.
Most California box truck operators need primary auto liability, physical damage coverage, and motor truck cargo insurance as a baseline package. Primary auto liability satisfies Motor Carrier Permit proof-of-insurance requirements, while physical damage protects the truck itself and cargo insurance covers goods in transit. Operators running crews or entering customer sites often add truckers' general liability and workers' compensation as well. The right combination depends on truck weight, cargo value, and how the business operates day to day.
Premiums vary widely because underwriters price on truck weight, cargo value, radius of operation, driver history, and claims record rather than a flat rate. A 16-foot appliance delivery truck with a clean driving record costs less to insure than a 26-foot moving truck carrying high-value household goods across a wide territory. Adding coverage layers like truckers general liability or workers' compensation increases the total premium but closes gaps that a truck-only policy leaves open. Getting an accurate quote requires gathering GVWR, cargo type, and driver information before contacting an agent.
The order works the other way: California requires proof of insurance as part of the Motor Carrier Permit application, so carriers typically secure a policy first and use it to satisfy the MCP insurance checklist. New carriers should apply for an MCP through the DMV and gather a CA number from the California Highway Patrol before submitting paperwork. The permit will not be issued until insurance documentation and any required workers' compensation proof or exemption are on file. Operators adding trucks to an existing fleet still need to confirm coverage meets current MCP requirements before dispatching a new vehicle.
Motor truck cargo insurance covers loss, damage, or theft of the goods being hauled inside the truck, while truckers' general liability covers non-auto business exposures like customer-site incidents. A dented appliance during transit is a cargo claim, while a driver damaging a customer's flooring while carrying that appliance inside is typically a general liability claim. Neither policy substitutes for the other, and delivery or moving companies that enter homes, warehouses, or job sites usually need both. Reviewing actual business activities with an agent helps confirm which combination applies.
Turnaround depends on how complete the submitted information is, but having GVWR, cargo description, radius, and driver details ready speeds up the process significantly. Carriers that gather documentation before contacting an agent typically avoid the back-and-forth that delays quotes and certificate issuance. SoCal Truck Insurance assigns a dedicated agent to walk operators through the process and provide proof of insurance needed for Motor Carrier Permit applications or customer contracts. Same-day support is available for urgent certificate requests through the agency's 24/7 line.